Why PPOs Are King: The Case for Nationwide Networks and Provider Freedom
Why PPOs beat HMOs for self-employed professionals, business owners, and frequent travelers: nationwide networks, no primary care gatekeepers, direct specialist access, and fewer authorization delays.
Private PPO • Provider Freedom
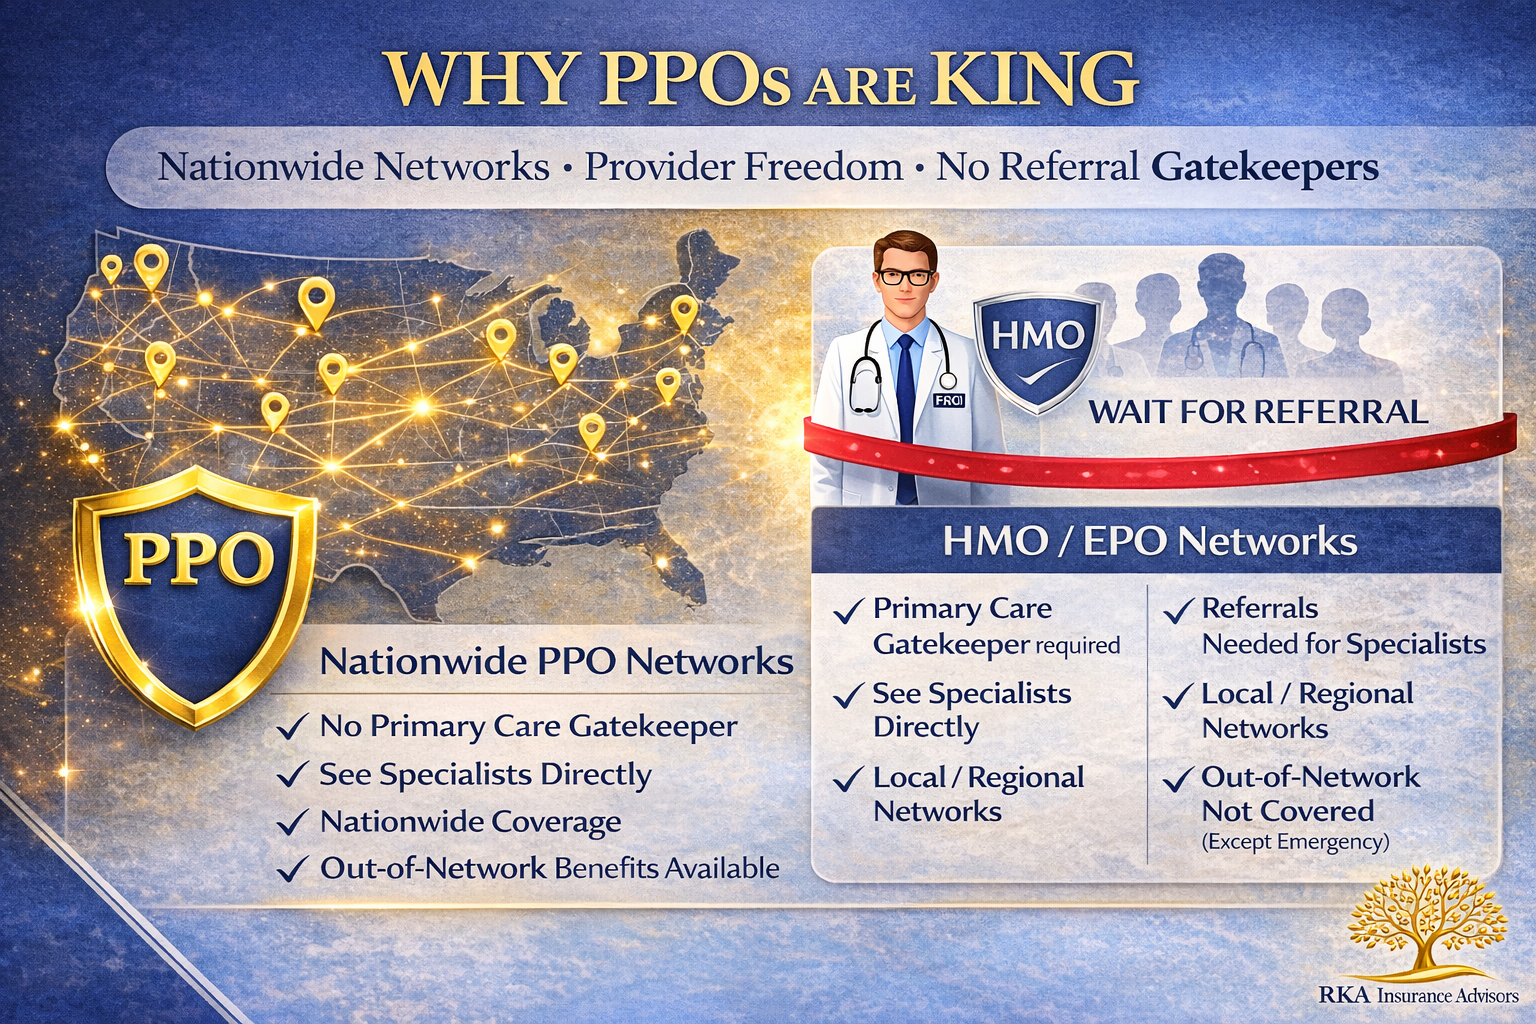
Why PPOs Are King: Nationwide Networks & Provider Freedom
What makes a PPO different
HMO / EPO (most marketplace plans)
- Primary care doctor (PCP) required
- Referrals needed for specialists
- Limited to a local network
- Out-of-network isn't covered (except emergencies)
- Authorization delays are common
PPO (Preferred Provider Organization)
- No primary-care gatekeeper required
- See specialists directly — no referrals
- Nationwide network coverage
- Out-of-network benefits available
- Fewer authorization requirements
Who benefits most from a PPO
Business owners & entrepreneurs
- Client meetings across multiple states
- Need care wherever business takes them
- Can't afford delays waiting for referrals
- Want specialist access without bureaucracy
Frequent travelers
- Snowbirds splitting time between states
- Remote workers and digital nomads
- Families with a second home
- Need consistent coverage anywhere
Specific provider needs
- Established relationship with a specialist
- Prefer specific hospitals or facilities
- Need access to top-tier medical centers
- Don't want to change doctors
High-income households
- Don't qualify for meaningful ACA subsidies
- Paying full price either way
- Want maximum flexibility and choice
- Prefer premium networks and providers
Real-world scenarios where a PPO wins
The entrepreneur in pain
HMO: back pain → see PCP first → wait for referral → wait for the specialist appointment → weeks of delay. PPO: back pain → call the orthopedist directly → appointment this week → faster treatment.
The traveling consultant
HMO: urgent care needed in Dallas → not in network → pay full cost, file a claim, hope for reimbursement. PPO: urgent care in Dallas → nationwide network → normal copay → done.
The specialist relationship
HMO: your cardiologist isn't in network → forced to switch → rebuild the relationship from scratch. PPO: your cardiologist is in the nationwide network → keep your doctor → continuity of care.
The imaging authorization
HMO: doctor orders an MRI → needs authorization → wait 5–7 business days → diagnosis delayed. PPO: doctor orders an MRI → schedule immediately → faster diagnosis and treatment.
The hidden costs of HMO restrictions
Many people pick an HMO to save on premium — but total cost is more than the monthly bill.
Time costs
- Waiting for a PCP visit before a specialist referral
- Authorization delays (5–7 days for imaging/procedures)
- Longer treatment timelines from referral requirements
- Lost productivity from delayed care
Out-of-pocket surprises
- Out-of-network urgent care while traveling = full cost
- Out-of-state ER = potential balance billing
- Preferred specialist not in network = start over
- Lab work at a non-contracted facility = surprise bills
Built for the self-employed
- You can't afford downtime — no paid sick leave; every day waiting on a referral is lost income. A PPO gets you to specialists immediately.
- Your work location varies — client sites, conferences, remote work; you need coverage that travels, not just your home county.
- You control your schedule — skip the PCP visit just to get a referral; see the specialist directly.
- You're paying full freight anyway — if you don't qualify for subsidies, PPO premiums are often comparable with far better access.
PPO myths, debunked
Myth: PPOs are always more expensive
For healthy applicants who don't qualify for subsidies, private underwritten PPOs often cost less than unsubsidized ACA plans — with better networks and lower deductibles.
Myth: You don't need nationwide coverage
Even if you rarely travel, emergencies happen. A car accident on vacation or a family emergency out of state — nationwide PPO coverage eliminates the surprise bills.
Myth: Referrals aren't a big deal
Referral requirements add 1–3 weeks to every specialist visit. For time-sensitive issues or busy professionals, that delay is costly.
Myth: All PPOs are the same
Network size varies dramatically. We verify your specific doctors are in-network before you enroll — not every "nationwide" PPO includes every provider.
When to choose a PPO — and when an HMO might work
Choose a PPO if…
- You're self-employed or own a business
- You travel frequently
- You have established specialist relationships
- You don't qualify for meaningful subsidies
- You value direct access without referral delays
An HMO/EPO might work if…
- You qualify for strong ACA subsidies
- All your doctors are in one local network
- You rarely travel or need out-of-area care
- You're fine with PCP gatekeeping and referrals
- Lowest monthly premium is your only priority
How RKA finds the right PPO for you
- Doctor verification first — we check your actual doctors, specialists, and hospitals against real PPO networks, not outdated find-a-doc directories.
- Multi-state coverage mapping — split time between states? We confirm both locations have strong coverage before you commit.
- Total cost comparison — premiums + deductibles + expected usage for HMO vs PPO; sometimes the PPO costs less once you count out-of-network exposure.
- Private vs. marketplace PPO — the marketplace has limited PPO options; we compare against private underwritten PPOs with broader networks and lower deductibles.
Ready for nationwide PPO freedom?
We'll verify your doctors, compare PPO options, and show you total cost — no referral requirements, no network restrictions.
Get Free Quotes Book a CallQuick FAQs
Are PPOs available on the ACA marketplace?
Some states offer limited PPO options on the marketplace, but many areas only have HMO/EPO plans. Private underwritten PPOs (off-exchange) often offer broader networks and better benefits for healthy applicants.
Do PPOs really cost more than HMOs?
For subsidized plans, yes. But if you don't qualify for subsidies, private PPO premiums are often comparable to unsubsidized HMO/EPO plans — with far better access and lower deductibles.
What does "nationwide PPO" actually mean?
Network coverage in all 50 states (or most). Specific provider availability varies — we verify your doctors are included, not just that the network exists in your state.
Can I switch from HMO to PPO mid-year?
ACA plans can only switch during open enrollment (or with a qualifying event). Private PPOs are available year-round if you qualify for underwriting.
For education only; network access and benefits vary by carrier and state. Always verify providers before enrollment. Private underwritten plans are subject to medical underwriting — not all applicants qualify. RKA Insurance Advisors is an independent, licensed health insurance brokerage (NPN 19540130). We do not offer Medicare. Call (561) 806-9913.