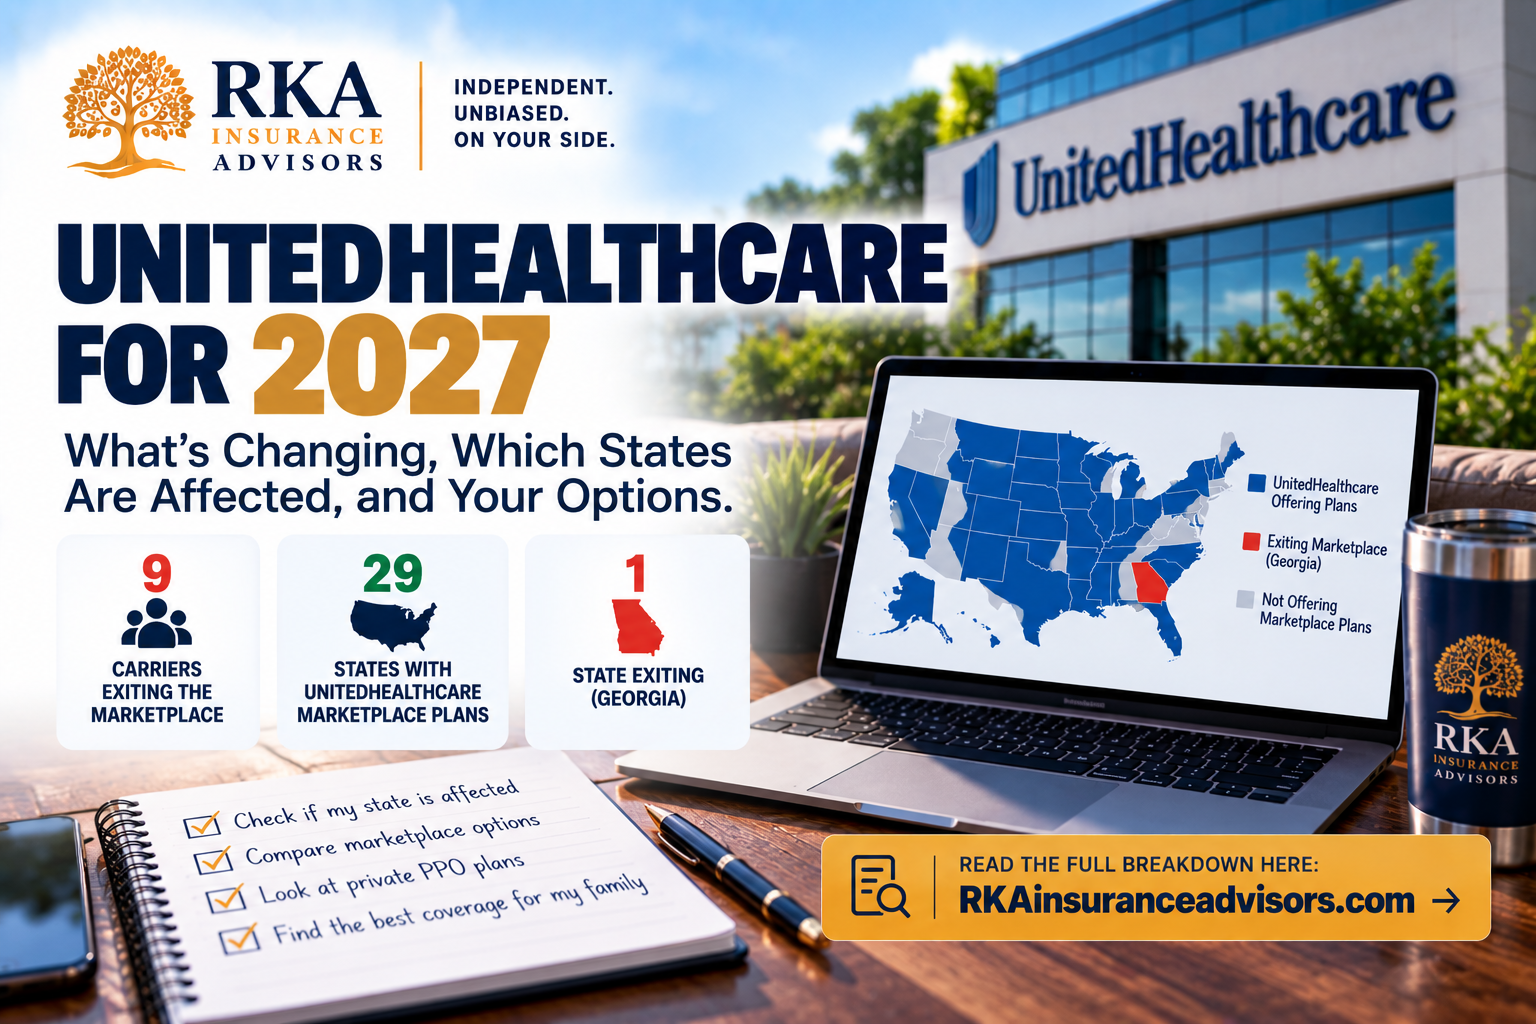
UnitedHealthcare for 2027
For 2027 UnitedHealthcare offers marketplace plans in 29 states and is leaving just one — Georgia. Here’s the full list and how to compare your options.

CareSource and Molina Are Leaving Ohio's ACA Marketplace in 2027
CareSource and Molina are both leaving Ohio for 2027 — about 54,000 Ohioans need new coverage. Here's how to compare a private nationwide PPO and marketplace plans before you're auto-switched.

UnitedHealthcare Now Covers More of Indiana for 2027
UnitedHealthcare expanded from 5 to 36 Indiana counties for 2027 — right as CareSource and Cigna exit. Here's how displaced members can compare a new plan or a private PPO.

Health Insurance for Self-Employed Georgians: What to Know for 2027
Georgia Access rates are jumping 20%+ for 2027 and both Cigna and UnitedHealthcare are leaving. Here's how self-employed Georgians can compare private PPO vs. marketplace and cut cost.

CareSource Leaving Indiana 2027
CareSource is leaving Indiana's marketplace for 2027 — ~60,000 members need a new plan. Your options, and how to keep your subsidy.

Baylor Scott & White Leaving Texas 2027
Baylor Scott & White is leaving Texas' marketplace for 2027 — ~100,000 members need a new plan. Your options, explained.

We Remember: September 11, 2001
Some days ask nothing of us but to stop, and to remember. On September 11, we honor the lives lost, the first responders who ran toward the danger, and the unity that rose out of that day. We remember.

2027 Open Enrollment Dates
2027 open enrollment opens Nov 1 — the key dates, the subsidy cliff, and how to compare marketplace vs. private nationwide PPO.

Cigna Leaving ACA Marketplace 2027
Cigna is leaving the ACA marketplace in 2027 — who's affected, key dates, and how to replace your plan without losing coverage.

1099 Contractor Health Insurance: How to Get Covered When Your Income Varies
When you're 1099, there's no employer plan and no steady paycheck to size a premium against. That makes two things matter more than usual: estimating income for a subsidy you can't predict, and the self-employed premium deduction. Here's how contractors get covered.

Getting Married? How to Compare Health Insurance Before You Merge Plans
Marriage is a qualifying life event — a 60-day window to optimize your coverage, not just merge it. For two working spouses, separate plans sometimes beat one combined plan on cost and network. Here's how to run the comparison before you default to "just join mine."

Oracle Layoffs & COBRA: What Your Coverage Will Cost and Cheaper Alternatives
Oracle cut roughly 21,000 roles over the past year. If you were one of them, the COBRA letter in your inbox is about to show you what your health plan actually costs. Here's how COBRA, ACA, and a nationwide private PPO compare —and how healthy people frequently cut the bill in half.

Using Gusto for Payroll and Health Insurance? One Option They Don't Show You
If you run payroll on Gusto, its health-insurance tab is Gusto's own in-house brokerage showing a limited menu of carriers — and it won't surface options outside that menu. This guide covers the one that often saves a healthy small team the most (an individually medically underwritten nationwide PPO, where each employee is underwritten into a broader, healthier pool), why standard small-group overprices a healthy team, how to keep Gusto for payroll while bringing your own broker, and when Gusto's built-in options still make sense.

Back-to-School Health Insurance for Self-Employed Parents: A Coverage Checkpoint
Back-to-school season is a natural coverage checkpoint for self-employed parents — sports physicals, school forms, new prescriptions, and kids who may be aging off your plan. This guide covers the five things to confirm before September, why a nationwide PPO often fits families better than an in-state marketplace HMO for specialists and travel-sports injuries, when a marketplace subsidy is still the smarter family move, and a tax perk many self-employed parents miss.

Health Insurance for Travel Nurses: PPO Coverage That Moves With You
Travel nurses change states every few months — most health plans don't keep up. Here's how nationwide private PPO coverage works for contract nurses, how to bridge gaps between assignments, and when the ACA marketplace still wins.

Lost Your Job or Left Corporate? How to Cut Your Health Insurance Bill in Half
Leaving a corporate job is one of the most common health insurance triggers. COBRA keeps your coverage but at full price — your share plus your employer's share. For healthy people, a private medically underwritten PPO often costs half as much with the same nationwide network. Here's how to make the switch.

Health Insurance for Gig Workers and 1099 Contractors: How to Get Covered
Gig and 1099 work spans rideshare to six-figure consulting — and none of it comes with benefits. Here's how independent workers really compare coverage: why the monthly premium is only the sticker price, how deductibles, copays, and out-of-pocket maximums decide what you actually pay, and why a nationwide PPO's in- and out-of-network freedom often beats an in-state HMO or EPO — plus when a marketplace subsidy still makes sense.

Is It Cheaper to Insure Your Family Separately From Your Employer's Plan?
Most employers heavily subsidize the employee's premium and contribute little or nothing toward a spouse or kids — so adding family to the group plan can cost hundreds a month. Here's the math nobody explains, and why "being on the same plan" matters less than you think.

Divorce and Health Insurance: What Happens to Your Coverage in 2026
Divorce ends the coverage you carried on a spouse's plan — usually within 30 days of the decree. For healthy, higher-income professionals who don' qualify for subsidies, a private medically underwritten PPO often costs far less than COBRA, with nationwide access and year-round enrollment.

GLP-1 Coverage Explained: Ozempic, Wegovy & Zepbound in 2026
Whether a plan covers a GLP-1 usually comes down to what it's prescribed for. Diabetes use is commonly covered; weight-loss coverage in 2026 is limited, shrinking, and almost always tied to prior authorization. Here's how each coverage path works — and what to check before you enroll.