2027 Open Enrollment Dates
2027 open enrollment opens Nov 1 — the key dates, the subsidy cliff, and how to compare marketplace vs. private nationwide PPO.
2027 Open Enrollment
2027 Open Enrollment: New Dates, Higher Costs & What Changed
The 2027 dates (and the confusion, cleared up)
What's solid
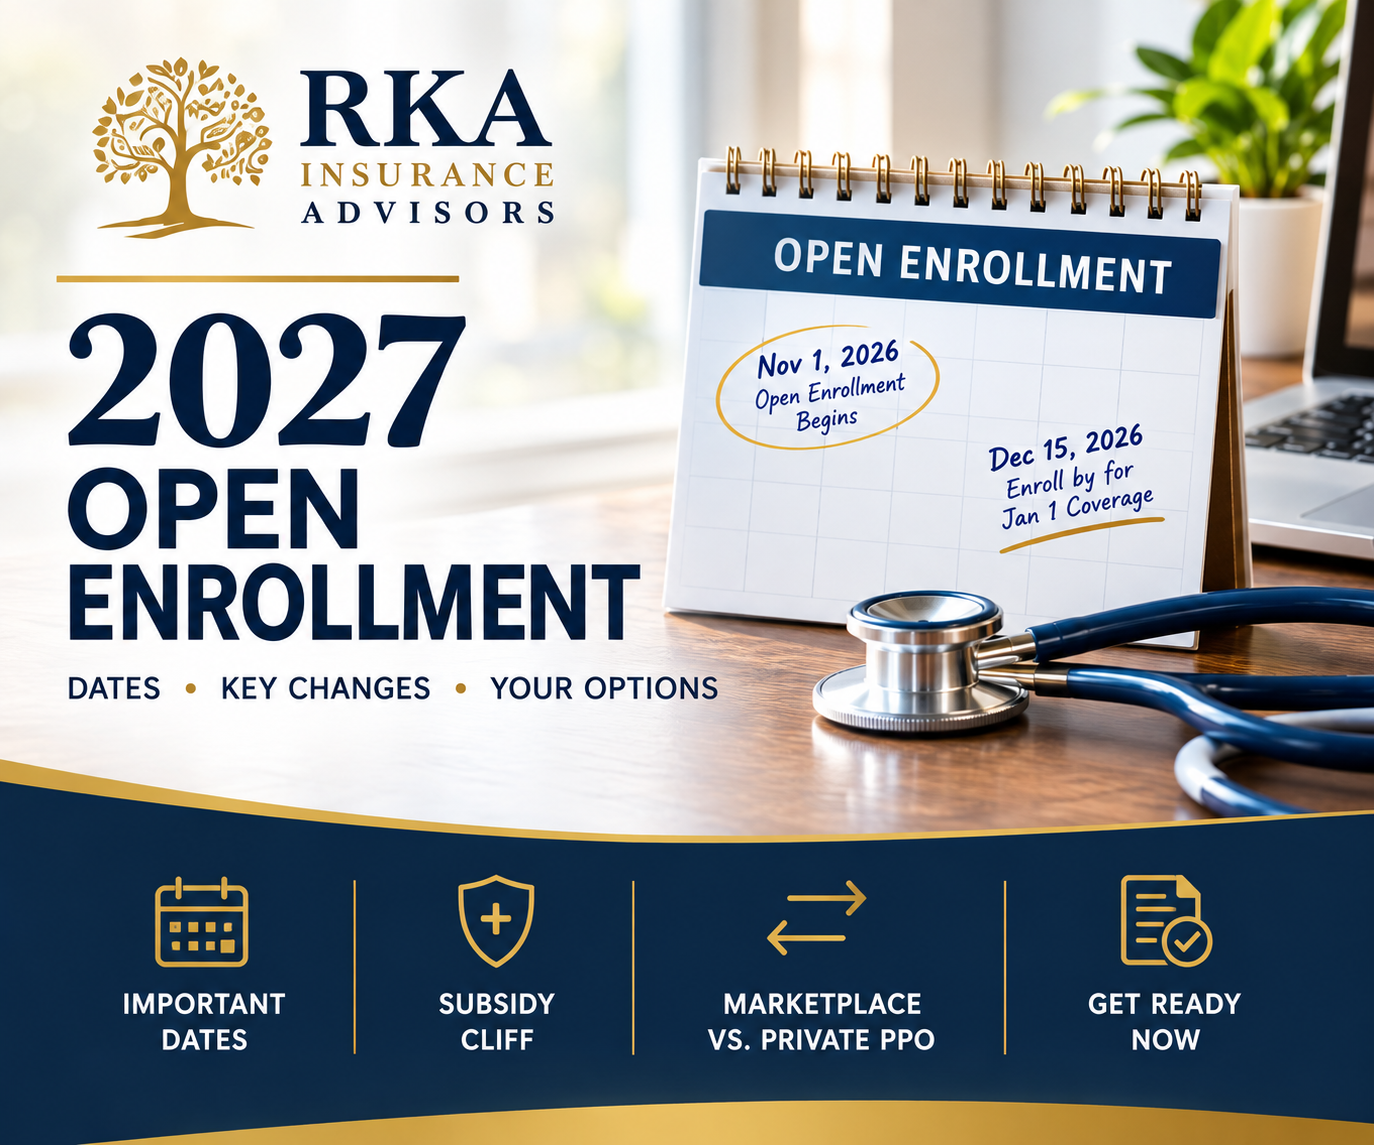
- Nov 1, 2026 — open enrollment opens
- Dec 15, 2026 — enroll by this date for coverage starting January 1 (true in every state)
- Miss Dec 15 and your start date is typically pushed to Feb 1 where a later window still applies
What's in flux
- A federal rule tried to end 2027 open enrollment on Dec 15 — but a court vacated it in June 2026
- So most states are expected to keep the Jan 15, 2027 end date, but it varies by state and could shift
- Bottom line: don't gamble on the late window — target Dec 15
What changed for 2027
The enhanced subsidies that lowered premiums from 2021–2025 expired at the end of 2025. For 2027 that means higher net premiums for many, and the return of the subsidy cliff: earn a dollar over 400% of the federal poverty level and you lose all marketplace subsidy. If your income is above that line, the marketplace charges full retail — which is exactly where a private plan often wins.
Your two ways to enroll for 2027
Private nationwide PPO
- Offered by only a limited number of agents — we're one
- Priced on your health, not income — often cheaper if you're healthy or above the cliff
- Broad nationwide network, no referrals, enroll year-round
- Medically underwritten — not everyone qualifies
A marketplace (ACA) plan
- Best if your income qualifies you for a subsidy
- Guaranteed issue — no health questions; covers maternity and pre-existing conditions
- Enroll during the open enrollment window above
- Networks often narrower (HMO/EPO), with referrals
What to do now
- 1. Check your income against the cliff for your family size — it decides whether the marketplace or a private PPO wins.
- 2. Compare both — full-price marketplace vs. a private nationwide PPO, on premium, network, and total cost.
- 3. Confirm your doctors and prescriptions are covered before you enroll.
- 4. Enroll by December 15 for January 1 coverage — don't rely on the later window.
Get your 2027 plan sorted before Dec 15
We compare private nationwide PPO plans and marketplace options — matched to your income, doctors, and budget — at no cost to you.
Get Free Quotes Book a CallFrequently asked questions
When does 2027 open enrollment start and end?
It opens November 1, 2026. The deadline to enroll for January 1 coverage is December 15, 2026 in every state. A rule that would have ended enrollment on December 15 was vacated in court, so most states are expected to run through January 15, 2027 — but this varies by state and can change, so target December 15 to be safe.
What is the subsidy cliff for 2027?
With the enhanced subsidies expired, if your household income is above 400% of the federal poverty level you get no marketplace subsidy in 2027 — you pay the full premium. For healthy households over the cliff, a private nationwide PPO is often the cheaper option.
Is the marketplace my only choice?
No. Besides a marketplace plan, we offer private, medically-underwritten nationwide PPO plans that only a limited number of agents can access — often cheaper and broader for healthy or higher-income households. We compare both.
What if I miss the deadline?
You may qualify for a Special Enrollment Period after a life event (job loss, marriage, a move, a new baby). And private PPO plans enroll year-round, so you're not locked out until next fall.
Related guides
This article is for general educational purposes and is not a substitute for personalized advice. Open enrollment dates and rules vary by state and are subject to change and ongoing litigation; confirm the current dates for your state before enrolling. RKA Insurance Advisors is an independent, licensed health insurance brokerage (NPN 19540130) that compares ACA marketplace and private, medically-underwritten nationwide PPO plans. Private plans are not ACA-compliant and are subject to medical underwriting — not all applicants qualify. We do not offer Medicare. Not insurance, legal, tax, or financial advice. Call (561) 806-9913.
Cigna Leaving ACA Marketplace 2027
Cigna is leaving the ACA marketplace in 2027 — who's affected, key dates, and how to replace your plan without losing coverage.
Coverage Alert • ACA Marketplace
Cigna Is Leaving the ACA Marketplace in 2027: What Members Need to Know
What's happening
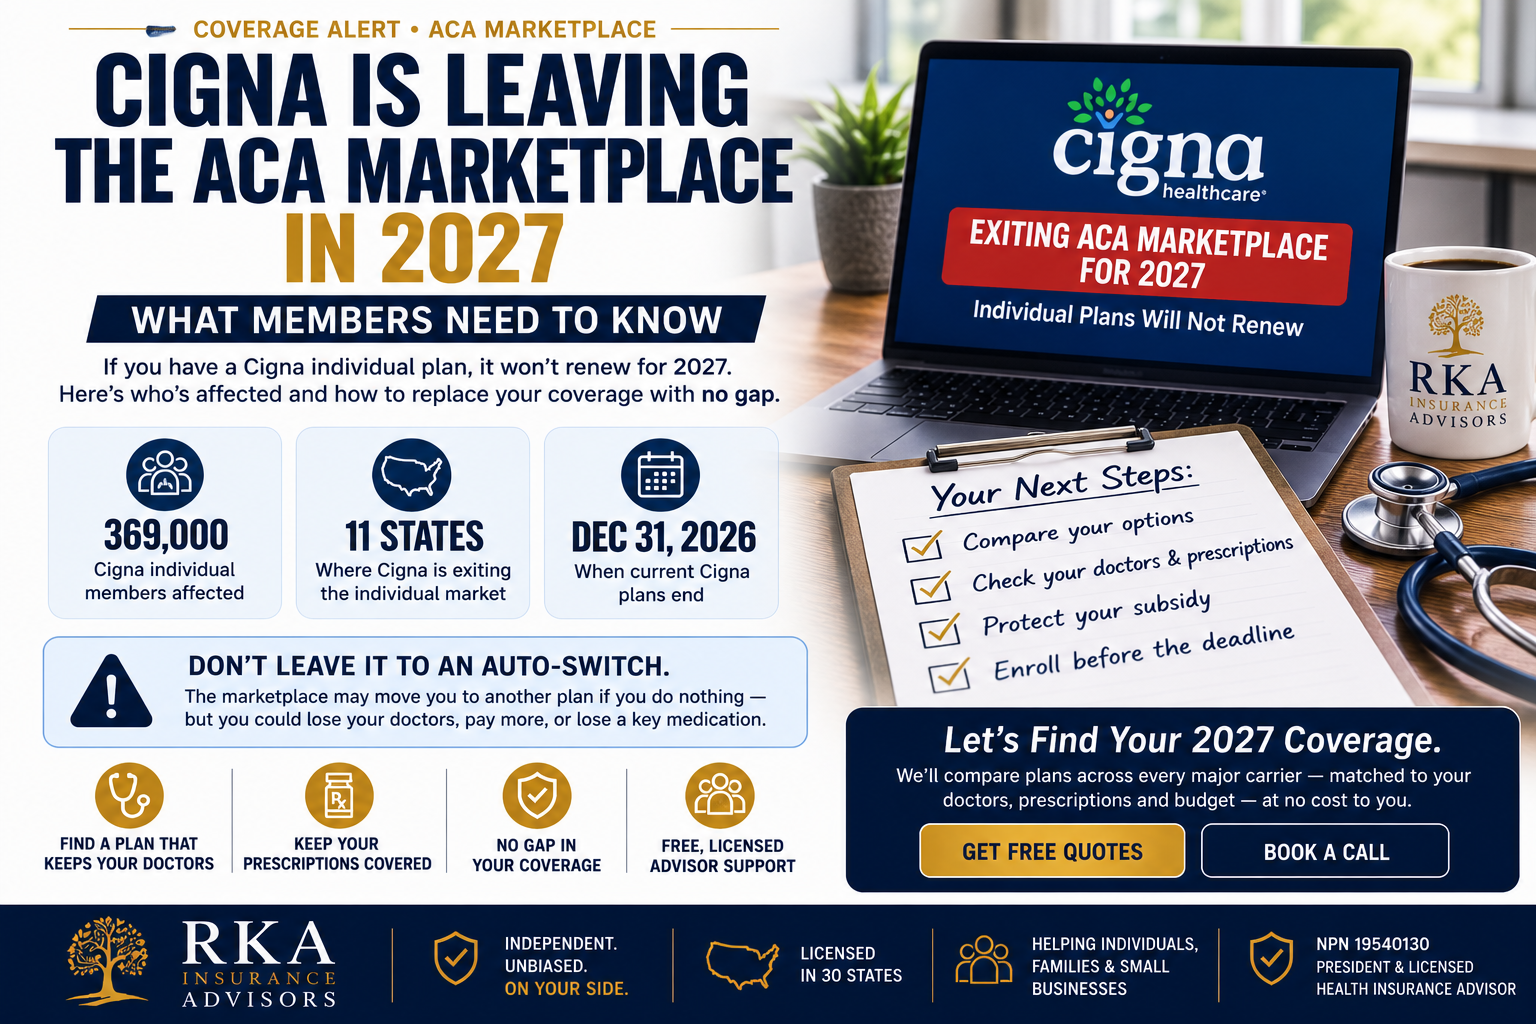
Cigna announced in April 2026 that it is leaving the individual ACA market to focus on its larger business lines. The result: Cigna individual and family plans will not be sold or renewed for 2027. This affects both on-exchange plans (through HealthCare.gov or your state's marketplace) and off-exchange Cigna individual plans. Employer group and Medicare products are not affected.
Your two ways to replace it
Private nationwide PPO
- Offered by only a limited number of agents — we're one
- Priced on your health, not your income — often cheaper if you're healthy or above the subsidy line
- Broad nationwide PPO network, no referrals, enroll year-round
- Medically underwritten — not everyone qualifies
A new marketplace (ACA) plan
- Best if your income qualifies you for a subsidy
- Guaranteed issue — no health questions
- Any subsidy you get today carries to the new plan
- Networks are often narrower (HMO/EPO), with referrals
What you should do now
- 1. Don't wait for the auto-switch. Choose your own 2027 coverage during open enrollment.
- 2. Compare both. Weigh a private nationwide PPO against a new marketplace plan — premium, network, and total cost.
- 3. Match it to your doctors and prescriptions. Confirm your providers are covered before you enroll.
- 4. Enroll before the deadline so your new coverage starts January 1 with no gap.
Key dates for 2027 coverage
Deadlines that matter
- Dec 31, 2026 — your current Cigna plan ends
- Nov 1, 2026 – Jan 15, 2027 — open enrollment (marketplace)
- Dec 15, 2026 — enroll by this date for Jan 1 coverage (no gap)
Good to know
- Private nationwide PPO plans enroll year-round — not tied to open enrollment
- Every marketplace plan is guaranteed-issue — no denial for pre-existing conditions
- Many of the same doctors are in other carriers' networks
Find your state
Cigna is exiting the ACA marketplace in 11 states. Choose yours for the details and next steps:
Losing your Cigna plan? See the option most brokers can't show you.
We compare private nationwide PPO plans and marketplace options — matched to your doctors, prescriptions, and budget — at no cost to you.
Get Free Quotes Book a CallFrequently asked questions
Is a new marketplace plan my only option?
No — and this is the part most people never hear. Besides a new marketplace (ACA) plan, you can replace a Cigna plan with a private, medically-underwritten nationwide PPO, which only a limited number of agents offer. It's priced on your health, uses a broad national network, and is often cheaper if you're healthy or above the subsidy line. We compare both.
What's the difference between marketplace and private PPO?
Marketplace plans are subsidized (if you qualify), guaranteed-issue, and often narrower networks. Private nationwide PPO plans are priced on your health, use broad networks with no referrals, and enroll year-round — but are medically underwritten, so not everyone qualifies. Most brokers only offer the marketplace side; we do both.
When does my Cigna plan end?
December 31, 2026. It will not renew into a Cigna plan for 2027.
Will I lose my doctors or my subsidy?
Not necessarily. Many of the same doctors are in other carriers' networks, and any marketplace subsidy carries to a new marketplace plan. A private PPO uses a broad national network. The key is comparing both before you enroll.
Does it cost anything to work with an advisor?
No. A licensed independent advisor is paid by the carriers, so there's no fee to you for help comparing private PPO and marketplace plans and enrolling.
Robert Adams
President & Licensed Agent, RKA Insurance Advisors · NPN 19540130 · (561) 806-9913
This article is for general educational purposes and is not a substitute for personalized advice. Plan availability, pricing, and enrollment dates vary by state; confirm details for your situation before enrolling. RKA Insurance Advisors is an independent, licensed health insurance brokerage specializing in private, medically-underwritten nationwide PPO plans in addition to ACA marketplace coverage. Private plans are not ACA-compliant and are subject to medical underwriting — not all applicants qualify. We do not offer Medicare. This content does not constitute insurance, legal, tax, or financial advice.
Open Enrollment Deadlines: What to Know & When to Enroll
Open enrollment deadlines explained — the main window, life-event special enrollment, and year-round private PPO options.
Guide • Open Enrollment
Open Enrollment Deadlines: What to Know & When to Enroll
Your four ways in, at a glance
Open Enrollment (most states)
- Late fall through mid-January, for coverage starting Jan 1 (or Feb 1 for later picks)
- The best time to compare plans and confirm your doctors and prescriptions
- We'll confirm this year's exact dates for your state
Special Enrollment (life events)
- Triggers: loss of coverage, marriage/divorce, birth/adoption, a move, and more
- Usually a 60-day window (varies by event and state)
- We help document it and enroll you before the deadline
Income-based special enrollment
- Certain income ranges can unlock a monthly enrollment window in some states
- Helpful if your income fluctuates or you missed the main window
- We check eligibility and project your income
Private PPO (if eligible)
- Some medically-underwritten plans enroll year-round
- We pre-screen underwriting and confirm nationwide access
- Great for travelers or households tied to specific doctors
How to avoid missing your window
- Set a reminder. Book a consult ahead of open enrollment so we can verify your doctors and run cost projections.
- Gather your details. Provider list (names and locations), prescriptions, and estimated income.
- Pick with confidence. We show total annual cost (premium plus likely usage) and confirm your start date.
We'll confirm your dates and handle enrollment
Send your providers and prescriptions. We'll line up Marketplace vs. private PPO options, confirm networks, and submit your application correctly and on time.
Get Free Quotes Book a CallQuick FAQs
Do state-based Marketplace dates differ?
Yes. Most states follow the standard late-fall to mid-January window, but several states run their own dates. We'll confirm the exact deadline for your state.
Can I switch plans mid-year?
Generally only with a qualifying life event that opens a Special Enrollment Period. Otherwise Open Enrollment is your main window — though a private PPO may let you enroll year-round if eligible.
Are private PPOs available in my state?
Often, yes — subject to medical underwriting. We pre-screen quickly and confirm nationwide network access before you apply.
For education only; eligibility, plan availability, and dates vary by state and carrier. Always review official Marketplace notices and plan documents. Private plans are medically underwritten — not all applicants qualify. RKA Insurance Advisors is an independent, licensed health insurance brokerage (NPN 19540130). We do not offer Medicare. Call (561) 806-9913.
Open Enrollment 2026: What You Need to Know
Premiums are rising again. 2026 Marketplace plans are pricier with higher deductibles and OOP limits. Here’s what’s driving it — and how to compare Marketplace vs Private PPO options before Open Enrollment.
Open Enrollment 2026: What You Need to Know
Important dates
Get Expert Guidance Today
We’ll verify your doctors and meds, compare Marketplace vs. Private PPO, and show clear costs—no pressure, just answers.
What’s changing for 2026?
- Medical inflation & utilization: Hospital and provider costs continue to ripple through next year’s premiums.
- Prescription drugs: High-cost specialty meds remain a driver; formularies and tiers can shift.
- Subsidy math: Income and household size determine savings. We’ll confirm your eligibility band before you choose.
- Networks: HMO vs PPO vs EPO—pick based on the doctors/hospitals you actually use, not just the premium.
How to choose the right plan (quick framework)
- Doctors & facilities first: We confirm in-network status and referral rules.
- Rx check: We price your actual meds across plans (tier, prior auth, step therapy, mail-order).
- True annual cost: Compare premium + expected usage (copays/coinsurance + deductible + max out-of-pocket).
- Access & travel: If you need multi-state flexibility or out-of-network options, consider PPO over HMO.
Quick FAQs
When should I enroll?
Enroll early. Dec 15 starts Jan 1 coverage; Jan 15 starts Feb 1 coverage.
Can private PPOs be cheaper than Marketplace?
Yes—especially for healthy households that don’t qualify for large subsidies. We’ll model both paths.
Can you confirm my doctors and hospitals?
Absolutely. We verify providers and prescriptions before we present options.
Bottom line
Open Enrollment 2026 is your chance to realign cost, access, and coverage. We’ll do the homework—net cost, doctors, medications, and network rules—so you can enroll with confidence.
Licensed in AL, CO, DE, FL, GA, IA, IL, IN, KY, KS, LA, MD, MI, MO, MS, MT, NC, NE, NV, OH, OK, SC, SD, TN, TX, UT, VA, WI, WV, WY
Open Enrollment & Your Plan Options
Open enrollment explained — metal tiers, networks, subsidies, and the private options most brokers skip.
Open Enrollment • Basics
Open Enrollment & Your Plan Options, Explained
Open enrollment is the period each year when you can sign up for health insurance or change your current coverage. In most states it opens November 1 and runs through mid-January for individual and family plans. Enroll by December 15 and coverage typically starts January 1; enroll after that (through the deadline) and coverage usually starts February 1. Some states run their own window on different dates — check with one of our benefit specialists for your state, or see the current-year guide linked above.
Marketplace metal tiers
- Bronze — lowest monthly cost, but higher deductibles and more out-of-pocket expense.
- Silver — middle-of-the-road; balances coverage and cost (and unlocks extra savings if you qualify).
- Gold — higher premium, stronger cost-sharing, lower deductibles and out-of-pocket exposure.
- Platinum — rare and only in a few counties; highest premium, lowest deductibles.
Networks: why the type matters
Most Marketplace options are HMO or EPO networks — limited to a local service area, covering you outside it only for emergencies. PPO networks are available in select areas and offer nationwide access to providers without referrals. If you travel, split time between states, or want freedom to see specialists directly, network type matters as much as price.
Subsidies (premium tax credits)
If your income falls between 100% and 400% of the federal poverty level, you may qualify for a premium tax credit that lowers your Marketplace cost — sometimes dramatically. The exact income cutoffs change each year, and earning over the top of the range means you pay full price (the "subsidy cliff"). We calculate your current-year subsidy and show your true net cost. More on the subsidy cliff →
Options beyond the Marketplace
Other options we can compare
- Short-term medical — often the most affordable; coverage for roughly 30 days up to (with some insurers) 12 months. More limited than major medical.
- Fixed indemnity — supplemental coverage that pays set cash benefits toward specific costs; a layer of protection on top of a plan, not a replacement.
- Healthcare sharing — members share medical costs via a monthly share amount; not insurance, with its own rules and limits.
Don't assume your current plan is still the best
Before you renew, talk to a benefits specialist — we'll compare Marketplace and private options, verify your doctors, and make sure you're not overpaying.
Get Free Quotes Book a CallFrequently asked questions
When exactly can I enroll?
Open enrollment opens November 1 and runs into mid-January in most states; some state marketplaces differ. See the current-year guide for exact dates, or ask us about your state.
Is the Marketplace my only choice?
No. Depending on your income and health, a private nationwide PPO or a supplemental option may be a better fit. We compare all of them for you.
How do I know I'm not overpaying?
We price your real annual cost — premium, deductible, copays, and out-of-pocket max — across every option and verify your doctors before you enroll.
For education only; eligibility, benefits, and availability vary by carrier and state. Always review official plan documents. Private plans are medically underwritten — not all applicants qualify. RKA Insurance Advisors is an independent, licensed health insurance brokerage (NPN 19540130). We do not offer Medicare. Call (561) 806-9913.