2027 Open Enrollment Dates
2027 open enrollment opens Nov 1 — the key dates, the subsidy cliff, and how to compare marketplace vs. private nationwide PPO.
2027 Open Enrollment
2027 Open Enrollment: New Dates, Higher Costs & What Changed
The 2027 dates (and the confusion, cleared up)
What's solid
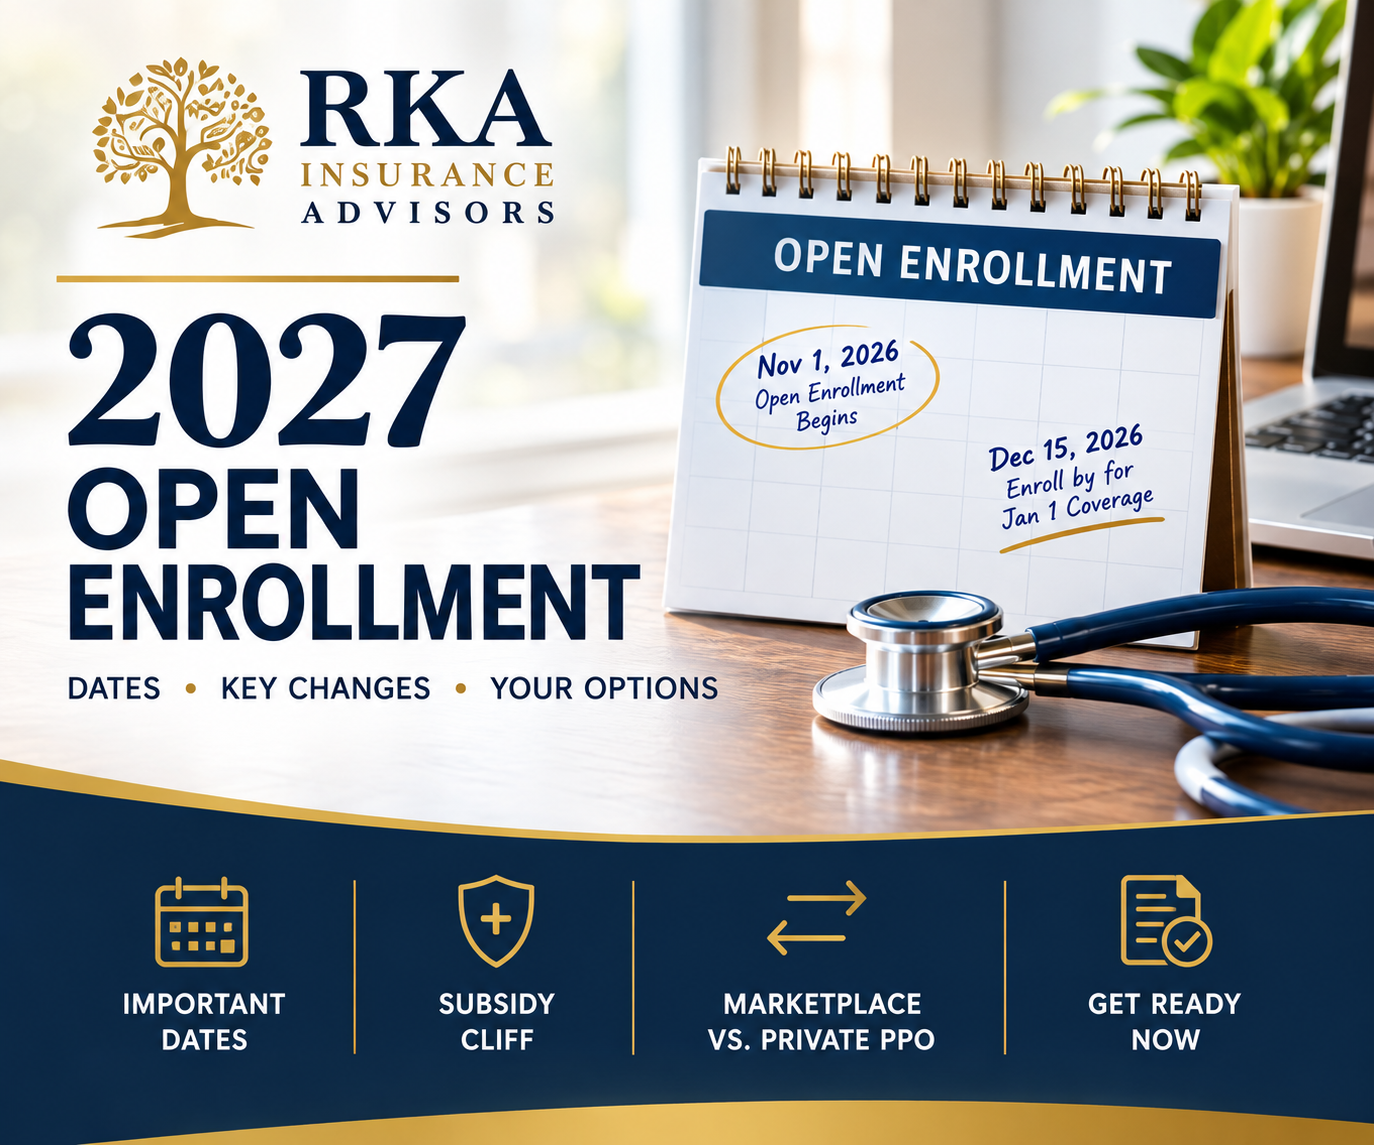
- Nov 1, 2026 — open enrollment opens
- Dec 15, 2026 — enroll by this date for coverage starting January 1 (true in every state)
- Miss Dec 15 and your start date is typically pushed to Feb 1 where a later window still applies
What's in flux
- A federal rule tried to end 2027 open enrollment on Dec 15 — but a court vacated it in June 2026
- So most states are expected to keep the Jan 15, 2027 end date, but it varies by state and could shift
- Bottom line: don't gamble on the late window — target Dec 15
What changed for 2027
The enhanced subsidies that lowered premiums from 2021–2025 expired at the end of 2025. For 2027 that means higher net premiums for many, and the return of the subsidy cliff: earn a dollar over 400% of the federal poverty level and you lose all marketplace subsidy. If your income is above that line, the marketplace charges full retail — which is exactly where a private plan often wins.
Your two ways to enroll for 2027
Private nationwide PPO
- Offered by only a limited number of agents — we're one
- Priced on your health, not income — often cheaper if you're healthy or above the cliff
- Broad nationwide network, no referrals, enroll year-round
- Medically underwritten — not everyone qualifies
A marketplace (ACA) plan
- Best if your income qualifies you for a subsidy
- Guaranteed issue — no health questions; covers maternity and pre-existing conditions
- Enroll during the open enrollment window above
- Networks often narrower (HMO/EPO), with referrals
What to do now
- 1. Check your income against the cliff for your family size — it decides whether the marketplace or a private PPO wins.
- 2. Compare both — full-price marketplace vs. a private nationwide PPO, on premium, network, and total cost.
- 3. Confirm your doctors and prescriptions are covered before you enroll.
- 4. Enroll by December 15 for January 1 coverage — don't rely on the later window.
Get your 2027 plan sorted before Dec 15
We compare private nationwide PPO plans and marketplace options — matched to your income, doctors, and budget — at no cost to you.
Get Free Quotes Book a CallFrequently asked questions
When does 2027 open enrollment start and end?
It opens November 1, 2026. The deadline to enroll for January 1 coverage is December 15, 2026 in every state. A rule that would have ended enrollment on December 15 was vacated in court, so most states are expected to run through January 15, 2027 — but this varies by state and can change, so target December 15 to be safe.
What is the subsidy cliff for 2027?
With the enhanced subsidies expired, if your household income is above 400% of the federal poverty level you get no marketplace subsidy in 2027 — you pay the full premium. For healthy households over the cliff, a private nationwide PPO is often the cheaper option.
Is the marketplace my only choice?
No. Besides a marketplace plan, we offer private, medically-underwritten nationwide PPO plans that only a limited number of agents can access — often cheaper and broader for healthy or higher-income households. We compare both.
What if I miss the deadline?
You may qualify for a Special Enrollment Period after a life event (job loss, marriage, a move, a new baby). And private PPO plans enroll year-round, so you're not locked out until next fall.
Related guides
This article is for general educational purposes and is not a substitute for personalized advice. Open enrollment dates and rules vary by state and are subject to change and ongoing litigation; confirm the current dates for your state before enrolling. RKA Insurance Advisors is an independent, licensed health insurance brokerage (NPN 19540130) that compares ACA marketplace and private, medically-underwritten nationwide PPO plans. Private plans are not ACA-compliant and are subject to medical underwriting — not all applicants qualify. We do not offer Medicare. Not insurance, legal, tax, or financial advice. Call (561) 806-9913.
Cigna Leaving ACA Marketplace 2027
Cigna is leaving the ACA marketplace in 2027 — who's affected, key dates, and how to replace your plan without losing coverage.
Coverage Alert • ACA Marketplace
Cigna Is Leaving the ACA Marketplace in 2027: What Members Need to Know
What's happening
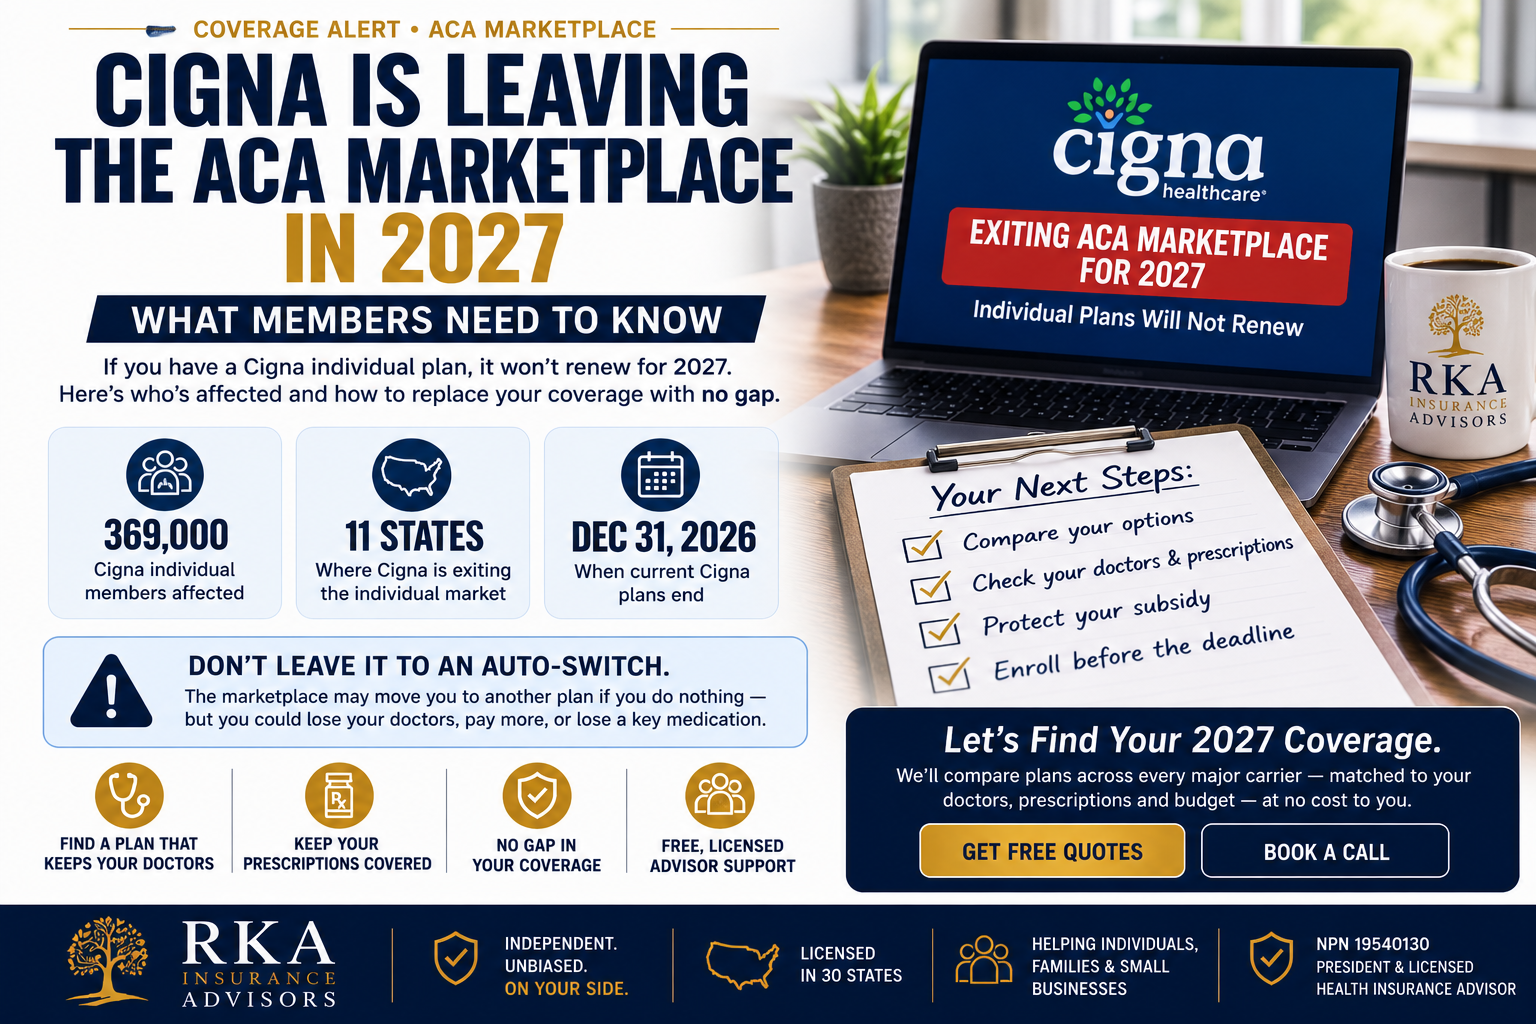
Cigna announced in April 2026 that it is leaving the individual ACA market to focus on its larger business lines. The result: Cigna individual and family plans will not be sold or renewed for 2027. This affects both on-exchange plans (through HealthCare.gov or your state's marketplace) and off-exchange Cigna individual plans. Employer group and Medicare products are not affected.
Your two ways to replace it
Private nationwide PPO
- Offered by only a limited number of agents — we're one
- Priced on your health, not your income — often cheaper if you're healthy or above the subsidy line
- Broad nationwide PPO network, no referrals, enroll year-round
- Medically underwritten — not everyone qualifies
A new marketplace (ACA) plan
- Best if your income qualifies you for a subsidy
- Guaranteed issue — no health questions
- Any subsidy you get today carries to the new plan
- Networks are often narrower (HMO/EPO), with referrals
What you should do now
- 1. Don't wait for the auto-switch. Choose your own 2027 coverage during open enrollment.
- 2. Compare both. Weigh a private nationwide PPO against a new marketplace plan — premium, network, and total cost.
- 3. Match it to your doctors and prescriptions. Confirm your providers are covered before you enroll.
- 4. Enroll before the deadline so your new coverage starts January 1 with no gap.
Key dates for 2027 coverage
Deadlines that matter
- Dec 31, 2026 — your current Cigna plan ends
- Nov 1, 2026 – Jan 15, 2027 — open enrollment (marketplace)
- Dec 15, 2026 — enroll by this date for Jan 1 coverage (no gap)
Good to know
- Private nationwide PPO plans enroll year-round — not tied to open enrollment
- Every marketplace plan is guaranteed-issue — no denial for pre-existing conditions
- Many of the same doctors are in other carriers' networks
Find your state
Cigna is exiting the ACA marketplace in 11 states. Choose yours for the details and next steps:
Losing your Cigna plan? See the option most brokers can't show you.
We compare private nationwide PPO plans and marketplace options — matched to your doctors, prescriptions, and budget — at no cost to you.
Get Free Quotes Book a CallFrequently asked questions
Is a new marketplace plan my only option?
No — and this is the part most people never hear. Besides a new marketplace (ACA) plan, you can replace a Cigna plan with a private, medically-underwritten nationwide PPO, which only a limited number of agents offer. It's priced on your health, uses a broad national network, and is often cheaper if you're healthy or above the subsidy line. We compare both.
What's the difference between marketplace and private PPO?
Marketplace plans are subsidized (if you qualify), guaranteed-issue, and often narrower networks. Private nationwide PPO plans are priced on your health, use broad networks with no referrals, and enroll year-round — but are medically underwritten, so not everyone qualifies. Most brokers only offer the marketplace side; we do both.
When does my Cigna plan end?
December 31, 2026. It will not renew into a Cigna plan for 2027.
Will I lose my doctors or my subsidy?
Not necessarily. Many of the same doctors are in other carriers' networks, and any marketplace subsidy carries to a new marketplace plan. A private PPO uses a broad national network. The key is comparing both before you enroll.
Does it cost anything to work with an advisor?
No. A licensed independent advisor is paid by the carriers, so there's no fee to you for help comparing private PPO and marketplace plans and enrolling.
Robert Adams
President & Licensed Agent, RKA Insurance Advisors · NPN 19540130 · (561) 806-9913
This article is for general educational purposes and is not a substitute for personalized advice. Plan availability, pricing, and enrollment dates vary by state; confirm details for your situation before enrolling. RKA Insurance Advisors is an independent, licensed health insurance brokerage specializing in private, medically-underwritten nationwide PPO plans in addition to ACA marketplace coverage. Private plans are not ACA-compliant and are subject to medical underwriting — not all applicants qualify. We do not offer Medicare. This content does not constitute insurance, legal, tax, or financial advice.